A November 16, 2026, acquittal in a case involving Ethereum block construction turned on a narrow legal question: did two validators make a materially false promise when they used a relay flaw to obtain transactions from a proposed block? The ruling did not decide that every form of maximal extractable value, or MEV, is lawful.
As reported on November 19, 2026, the case also had a connection to institutional staking. BlackRock had cited the prosecution in the prospectus for its iShares Staked Ethereum Trust ETF as a potential risk to MEV-related staking revenue.
How the proposed block was exposed
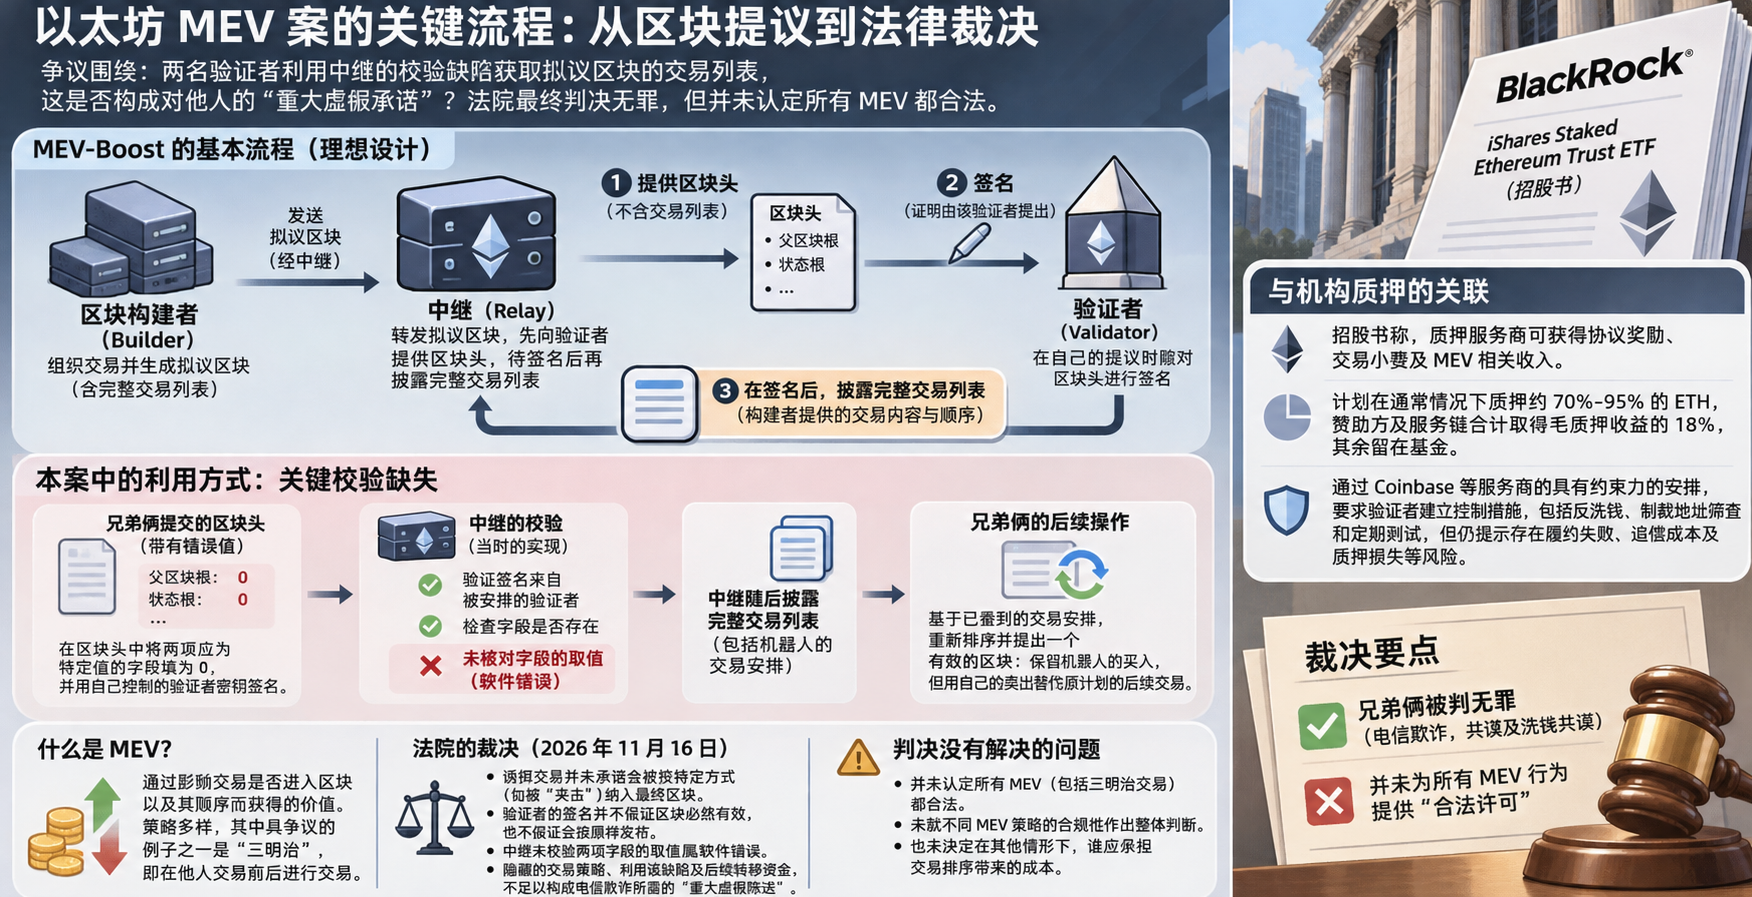
MEV is value gained by influencing which transactions enter a block and in what order. It includes different strategies; one contested example is a sandwich, in which a bot trades before and after another user’s transaction. The three traders described as victims in this case operated bots seeking such opportunities.
Under the MEV-Boost arrangement described in the court record, a builder sends a proposed block through a relay to the validator due to propose a block. The validator initially receives a block header rather than the full transaction list. After the validator signs, the relay reveals that list.
Court records say Anton and James Peraire-Bueno studied the bots from late 2022, established 16 validators and tested transactions intended to attract them. On April 2, 2023, when one of their validators had a proposal opportunity, they placed eight bait transactions in the public pending-transaction queue. The bots submitted bundles designed to trade around those transactions.
The brothers signed a header with zeroes in two fields that should have contained specific values: the parent-block root and state root. According to the ruling, the Ultrasound relay checked that the signature came from the scheduled validator and that the fields existed, but did not verify their values before releasing the full transaction list. Ethereum nodes would reject the resulting invalid block. Having seen the bots’ intended trades, the brothers proposed a valid, reordered block that retained a bot’s purchase but replaced the expected subsequent trades with their own sale.
Prosecutors initially described the episode as yielding approximately $25 million in about 12 seconds. That figure is the prosecution’s characterization, not an independent civil accounting of every loss. At trial, one bot operator gave an example in which its algorithm was willing to exchange roughly $2.3 million in USDC for SHIB worth about $8.25 at the then-current price, expecting an immediate sale at a more favorable price.
What the acquittal did—and did not—settle
U.S. prosecutors charged the brothers in May 2024 with wire fraud, conspiracy to commit wire fraud and conspiracy to commit money laundering. A nearly four-week trial ended in a mistrial in 2025 when the jury could not reach a unanimous verdict. After a trial without a jury, a federal judge acquitted them on November 16, 2026.
The prosecution argued that the bait transactions and signed header conveyed false promises about how the block would be published. The judge rejected both theories. A pending transaction did not promise that a bot could sandwich it in a final block. Nor did the validator’s signature guarantee that the proposed block was valid or would be published unchanged. The ruling noted that the relay operator acknowledged the failure to check the two fields as a software error. The judge also found that concealed trading tactics, exploitation of that flaw and subsequent fund transfers did not substitute for the material misrepresentation required for wire fraud; the money-laundering conspiracy charge depended on proceeds from that alleged fraud.
That is a finding about the charged conduct and the proof offered, not a blanket approval of sandwich trading or a determination of the legality of all MEV strategies.
Why the case appeared in a staking prospectus
BlackRock’s March 2026 prospectus said its staking providers could receive protocol rewards, transaction tips and MEV-related revenue. It warned that a finding that MEV violates applicable law could disrupt the fund’s staking program and affect the value of its shares. The prospectus anticipated staking approximately 70%–95% of the fund’s ETH under ordinary circumstances and said the sponsor and service chain together would receive 18% of gross staking rewards, with the remainder retained by the fund.
Those disclosures do not say the fund operated sandwich bots or participated in the relay exploit. They do show why the legal treatment of block-ordering revenue matters to a staking product. The prospectus also describes legally binding arrangements through Coinbase that require validators to maintain controls including anti-money-laundering measures, sanctions-address screening and periodic testing. It cautions that failures by Coinbase or validators, recovery costs and staking losses could still affect the fund and its holders.
The distinction illustrated by the case is between a signature that software accepts, a block that the network will accept, and an obligation that a court can enforce. The acquittal resolved the criminal charges against the brothers; it did not resolve every question about who bears the costs of transaction ordering or how particular MEV revenue is generated.